Chat with us, powered by LiveChat

Commercial Card Interchange Service (CCIS): What Merchants Pay

What is CCIS?

CCIS stands for Commercial Card Interchange Service. The quickest way to understand it is to follow the chain, because each term is really defined by the next.

CCIS→ Commercial Card Interchange Service.
Commercial Card Interchange Service→ When the credit card processor fixes the interchange.
Fixing the interchange→ Also called Data Enhancement.
Data Enhancement→ Filling in the data your file is missing so the transaction clears at the lowest interchange rate.

In plain terms, Data Enhancement is when the file your processor receives is missing data, and that data gets filled in, either by a data-enhanced gateway or by the processor. It completes the file so the transaction clears at the lowest interchange rate. A transaction that could have settled at 3.25% now settles at 1.95%.

If a merchant wants the lowest processing cost, it starts with making sure the right data gets passed, in the correct format. For big merchants, this is not a “hope for the best” kind of thing.

$10M+Some of our larger clients were losing over $10,000,000 a year. Not from bad rates, but from data not being passed correctly.

Their actual processing fees were not that bad. At that size they had negotiated a pretty good deal, partly because, as a global household name, the processor wanted to come in low enough to win the account. However, they were not using the correct gateway or utilizing CCIS.

What CCIS actually costs you

“The issue I have with CCIS is that it feels like paying the robbers to make sure no one else robs you.”

Credit card companies make it difficult for transactions to settle at the lowest interchange fees by adding stringent rules. Then they came up with a solution to fix it for you, called CCIS. Another processor calls it I/C, an Interchange Clearing Fee. It is when the processor fixes the transaction for 75% of the savings.

Before you think this is a good deal, let’s do the math and shine a little more light on it.

A $500 transaction that would downgrade from missing data
Saved by fixing it (about 85 basis points)$4.25
Processor’s CCIS fee: 75% of the savings ($3.19). You keep:$1.06
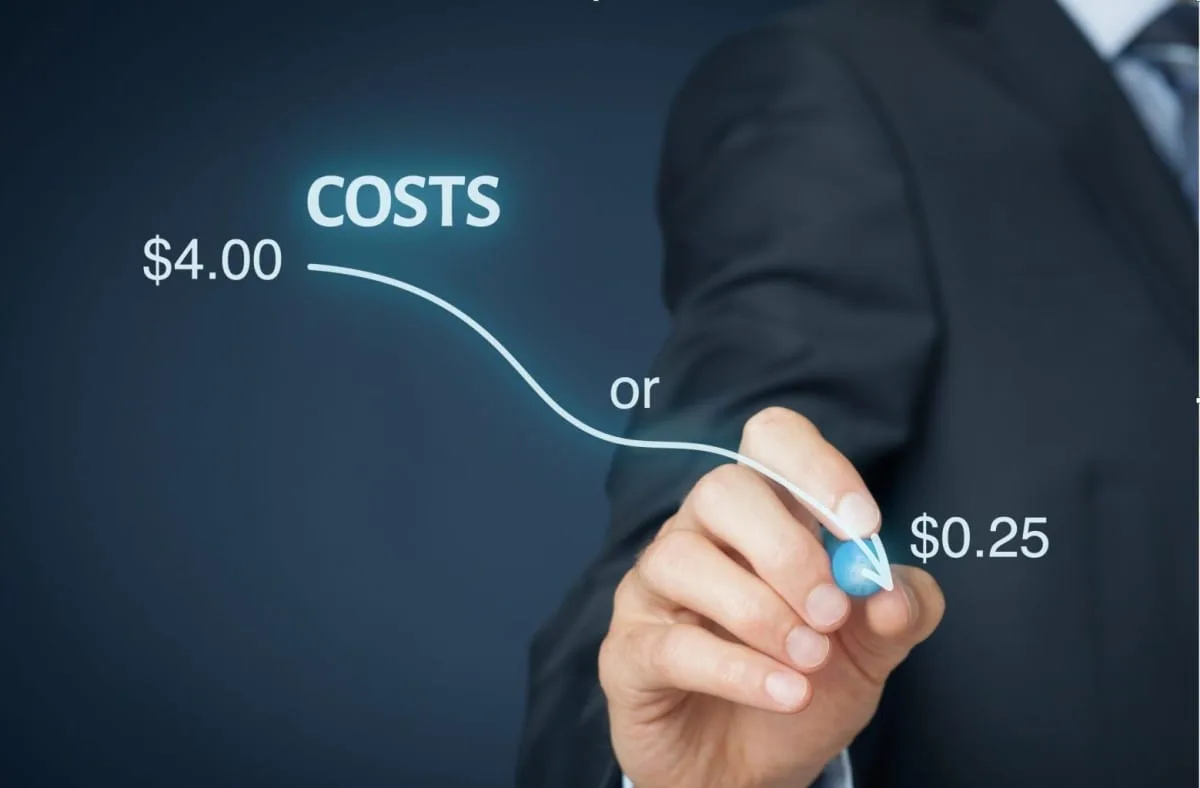
Third-party fee: 5 basis points ($0.25). You keep:$4.00

Same $4.25 saved, same transaction. The processor hands you $1.06 and tells you to be happy, because without them you would have lost the whole $4.25. A third party saves you the identical amount and gives you $4.00.

How to find CCIS on your statement

Different processors call it different names. Look for any of these line items:

I/CInterchange Clearing FeeCCIS

“I/C” is short for Interchange Clearing Fee. If you are not sure, look at every line-item fee and check it on our How to Read Your Merchant Statement page. It will tell you whether it is a real fee or not.

Your two options

Same fix, very different outcome
Option A: your processor fixes it Option B: a third party fixes it
Fee: 75% of the savings.

On our $500 example, you keep $1.06.

Fee: 5 basis points.

On our $500 example, you keep $4.00.

I think it is an easy decision. The only exception is when your ERP or POS blocks third parties to increase profits and prevent you from getting help.

But to be clear: if you have transactions not settling at the lowest interchange, doing nothing is the worst thing a merchant can do. You are handing the biggest bonus to those who are part of the processing-network family. The very ones making it hard are winning even more.

If you don’t know whether you have transactions downgrading, the best thing you can do is take advantage of our free audit. No strings, no credit card, nothing to sign, and zero impact to you. Then you will know how much money is walking out the back door every month when it could be used to grow your business.

Click here to schedule a call and learn how easy it is to fix this, or get started today with your free audit.

The other names for the same fee

The naming is not standardised, and that is part of why this charge goes unquestioned for years. The same arrangement appears as an Interchange Clearing Fee, as I/C, as CCIS, and as Commercial Card Interchange Service, depending on who sends the statement.

If you have been searching for what an Interchange Clearing Fee is, this page is the answer: it is the processor charging you a share of the money it saves by completing data your file was missing. The mechanics above apply to it exactly.

Worth noting the effect of the naming. A merchant who queries “CCIS” with their processor and gets a reasonable-sounding answer will not necessarily connect it to the Interchange Clearing Fee they were told about at a different company two years earlier. Four names, one arrangement, and no obvious way to compare.

Related
CCIS is a real network charge with a confusing name. Others are not real at all. Our guide to merchant account fees and which ones your processor invented lists the names that turn up most often and shows how to verify any of them at the network.

Whether this applies to you at all

This matters most if you accept business, corporate or purchasing cards, which in practice means B2B. Those card types sit in the interchange categories with the heaviest data requirements, so they are the ones that downgrade when fields are missing.

If your volume is overwhelmingly consumer cards, there is much less to fix and much less at stake. The fee should be small or absent, and if it is neither, that is a question worth asking.

Three things to ask your processor, in this order.

  • How many of my transactions downgraded last month, and what did it cost me? Without that number nobody can tell you whether any of this is worth paying for.
  • What exactly am I being charged for the fix, as a percentage of the saving? Not a dollar figure. The share is the number that matters.
  • Can my gateway pass the data itself? If a data-enhanced gateway can populate the fields, you may not need the service at all.

More detail on the gateway route is in strategies to help lower your credit card fees, and the underlying data programme is covered on Visa’s Commercial Enhanced Data Program.

Frequently asked questions

What is an Interchange Clearing Fee?

It is a charge for fixing your own transaction data so the transaction settles at a lower interchange rate. The processor fills in the fields your file was missing, the transaction stops downgrading, and the processor takes a share of the saving. Abbreviated to I/C on many statements, and called CCIS, Commercial Card Interchange Service, by others.

Is an Interchange Clearing Fee the same as CCIS?

Yes. Different processors use different names for the same service. If you see I/C, Interchange Clearing Fee, CCIS or Commercial Card Interchange Service on a statement, you are looking at the same arrangement.

Is the Interchange Clearing Fee a legitimate charge?

The service behind it is real, and the saving is real. What is worth questioning is the price. Charging 75% of a saving created by fixing data is a pricing choice, not a cost, and third parties do the identical job for around 5 basis points.

How much does an Interchange Clearing Fee cost?

Commonly 75% of the interchange saved. On a $500 transaction saving 85 basis points, that is $3.19 of the $4.25 saved, leaving the merchant $1.06. A third party charging 5 basis points would take $0.25 and leave the merchant $4.00.

Can I just remove the fee?

Removing it without fixing the underlying data problem makes you worse off, because the transactions go back to downgrading and you lose the full saving rather than part of it. The move is to change who does the fixing and what they charge, not to stop fixing it.

Which merchants does this affect most?

Anyone taking business, corporate or purchasing cards, which usually means B2B. Those card types carry the interchange categories with the most demanding data requirements, so they are the ones that downgrade when data is missing. Merchants taking mostly consumer cards see far less of this.

Find out how much is walking out the back door every month. The audit is free: no strings, no credit card, nothing to sign.

Get My Free Auditor call 800-672-1292

Read More

Check out our other insights here

Bank of America Credit Card Processing: What It Costs and What to Watch
Bank of America logo

If Bank of America handles your credit card processing, go and pull your last three statements before you read any further. We have watched accounts at that bank move from four basis points to over forty, and the businesses paying it were told the new
View

Do You Have Risk Fees On Your Credit Card Processing Statement?

Man reading credit card processing statement

Do you have a “Risk Fee” on your credit card processing statement?

No? Good. You are luckier than a lot of merchants, and you should keep reading anyway.

View

Want to talk?

As seen on