Chat with us, powered by LiveChat

Strategies To Help Lower Your Business’s Credit Card Fees

By Robert Day, Managing Partner at weAudit. A version of this article was first published by the Forbes Business Council.

As a merchant you have probably taken calls from companies promising to lower your credit card fees. What should surprise you is that they make that promise without having seen a single one of your statements. How is that possible?

Because processing fees are made up of many components across several categories, and there are a lot of ways to inflate and hide the pieces. Someone can promise you a saving without knowing anything about your account, because they are not really promising to lower your costs. They are promising to change one number you already look at.

Where the real money is
Interchange is usually the largest part of your bill, and it is not a fixed price. It depends on how much data travels with each transaction. Send more data and the same sale can clear at a materially lower rate.

The fee groups worth knowing

Discount fees are charged by the processor, usually as a percentage of the transaction (for example 0.05%) or as a flat amount per transaction (for example five cents). Occasionally, though rarely, both apply. The useful thing about these is that they are often negotiable.

Dues and assessments are charged by the card networks themselves, Visa, Mastercard, Discover and American Express. These are not negotiable and they vary between networks. Anyone promising to cut them is not being straight with you.

If you want the full anatomy of a processing bill, credit card processing fees explained goes through it layer by layer.

How to actually reduce the rate

The answer lies in how your transactions are processed. Interchange is typically the largest component, so lowering the rate at which your transactions settle is where the savings are.

Use a level three payment gateway

A level three gateway passes more data with each transaction. The more data that travels, the lower the interchange.

The size of that difference surprises people. A transaction clearing above 3.5% may be able to clear below 2%. Even a single point matters: if your effective rate is 3% and you get it to 2%, that is a 33% cut in your processing costs.

One caveat. If your business mostly takes consumer cards, this will not move the needle much. If you accept business, corporate or purchasing cards, it can be a game changer.

Understand what “data in, data out” means

A level three gateway does not create data. It passes along what your system gives it, and qualifying for the lowest interchange takes an average of around thirty fields. If your system is not populating them, the gateway cannot help you.

That is what data-enhanced gateways are for. They populate the required fields automatically, so you can reach the lower rates without the manual entry a plain level three setup demands. The same territory is covered in more depth on Visa’s Commercial Enhanced Data Program.

Two steps, in this order

1. Request a detailed interchange downgrade report. Ask your processor for the transactions that did not qualify for the lowest rate, and what those downgrades cost you. That number tells you what an upgrade is actually worth before you pay anyone for one.

2. Compare the cost of the solutions properly. Many processors offer a data enhancement service, and in my experience they take between 50% and 80% of the interchange savings. A data-enhanced gateway often comes at little or no extra cost and lets you keep most of it. Those two options can look identical on a sales call and are not remotely the same deal.

What that difference looks like in money

Take a $500 purchasing card transaction. The data gets enhanced, meaning the missing fields are added so the transaction clears at the lowest rate, and interchange drops by 0.85%, which is about the average I have observed. That is a saving of $4.25 on that one sale.

Same saving, two ways of paying for it
Option A, a processor’s data enhancement service. Many charge 75% of the savings. You saved $4.25, they take $3.19, you keep $1.06.

Option B, a data-enhanced gateway. Often around 0.05% of the transaction plus 15 cents. On $500 that is 40 cents, so you keep $3.85.

A difference of $2.79 on one transaction. At a thousand such transactions a month, that is $2,790 a month, or $33,480 a year.

That is the whole argument for reading the pricing rather than the promise. Both options deliver the identical interchange saving. Only one of them lets you keep it.

Consider an audit

Several companies, mine included, specialise in helping merchants lower processing fees and in auditing what they are already paying. Be careful though. Many will try to lock you into a contract, which makes it hard to leave if the service does not deliver what was promised. Look for no-contract, transparent arrangements. A search will find you firms in this space, but do the research before you choose.

If you want to know what your statement is telling you before you speak to anyone, the statement decoder covers what the individual line items mean.

Find out what your downgrades are costing
Send us a recent statement. Downgrades are one of the first things we look for, and they are usually the largest recoverable number on the account.

Get Your Free Audit

Get Your Free Audit  |  Schedule A Free Consultation

Subscribe to insights  |  Read more Insights  |  Submit an article idea

Read More

Check out our other insights here

Bank of America Credit Card Processing: What It Costs and What to Watch
Bank of America logo

If Bank of America handles your credit card processing, go and pull your last three statements before you read any further. We have watched accounts at that bank move from four basis points to over forty, and the businesses paying it were told the new
View

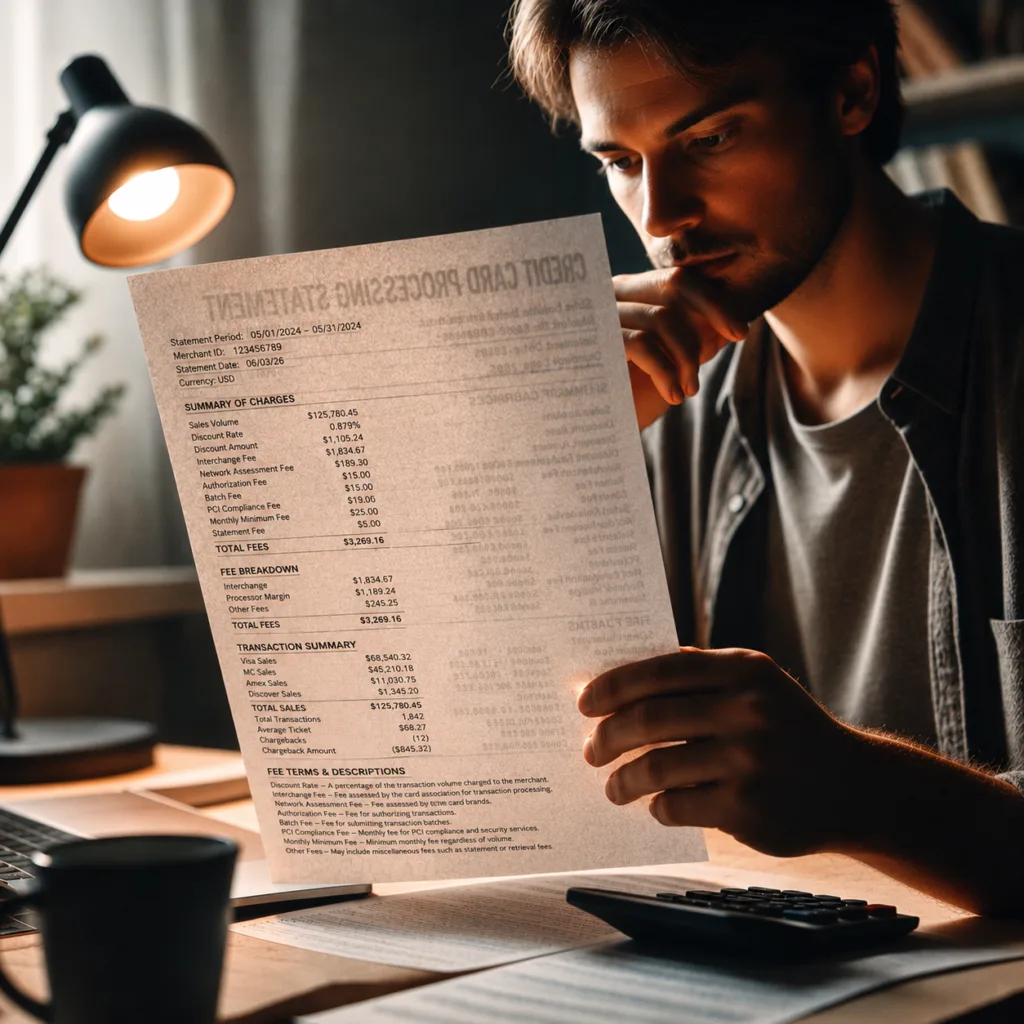
Do You Have Risk Fees On Your Credit Card Processing Statement?

Man reading credit card processing statement

Do you have a “Risk Fee” on your credit card processing statement?

No? Good. You are luckier than a lot of merchants, and you should keep reading anyway.

View

Want to talk?

As seen on