Chat with us, powered by LiveChat

What Merchants Should Consider Before They Surcharge

By Robert Day, Managing Partner at weAudit. A version of this article was first published by the Forbes Business Council.

With processing fees rising, more businesses are surcharging, or looking hard at it. Many tell us they feel stuck between a rock and a hard place: pay the higher fees, or take a risk trying to pass them on. There are other options, and there are three things worth understanding before you commit to this one.

Some companies in the card industry have been accused of overcharging merchants or applying unauthorized fees, which some attribute to the lack of regulation in the space. When the major processors went public they came under the same pressure as any public company to deliver larger profits. The difference, in my view as someone whose company audits processing fees, is that most industries sit in a free market that keeps pricing honest. If a business charges too much, you buy elsewhere. Merchant processing does not work that way, because most merchants cannot tell what they are being charged in the first place.

The short version
Surcharging is legal in most places and it is genuinely difficult to do correctly. Before you take on that compliance burden, find out whether the fees you are trying to pass on are even the right size.

1. The consequences of breaking the surcharging rules

In my experience it is uncommon, but a merchant can be blacklisted by the card networks for violating processor rules, including the rules on surcharging. It is rare, but a business that gets a warning and keeps breaking the rules can have its ability to accept cards permanently revoked.

For most businesses, that alone would be catastrophic. It is worth weighing that against whatever the surcharge is expected to recover.

2. Who is actually liable when it goes wrong

Read your processing agreement. You may find an indemnity clause saying the processor cannot be held accountable for anything.

Here is the problem with that. If the processor sets up your surcharging program, and the indemnity clause means they carry no responsibility for it, then a compliance failure in a program they built lands on you. The party with the expertise is not the party carrying the risk.

3. The rules and the laws do not agree with each other

Visa’s surcharging rules do not perfectly align with Mastercard’s, and both differ from American Express. In some cases they are in direct opposition.

Visa caps surcharging at 3%. Mastercard sets its limit at 4%. Both prohibit surcharges on debit cards. American Express, however, requires that all card types be treated equally, which means a merchant applying a surcharge can be non-compliant from an Amex rules perspective in certain scenarios, according to Worldpay.

Then layer the state laws on top. Some states ban surcharging outright. Others permit it but impose rules that are easy to fall foul of. A merchant who checks a chart, sees their state is not on the banned list, and concludes they are fine has only answered half the question.

Colorado, for example, sets a maximum surcharge of 2% of the transaction, even where the business is paying the processor 3%. And the customer’s location matters too: Missouri does not ban surcharging, but if a buyer in Connecticut orders from a company in Missouri, Connecticut does. Familiarise yourself with your own state’s rules, and consider having someone validate the process before you switch it on.

What businesses can do instead

In my view, surcharging does not have to be the answer. The answer is to find out whether the processing fees can be lowered in the first place.

Do not simply charge your customers 3%. It can cost you more than it recovers. Just because someone completes the sale does not mean they will not look elsewhere next time. The easiest way to understand this is to ask how you feel, and what you do, when it is done to you.

To lower your fees, consider working with a firm that will give you a free audit to see whether your processor is overbilling you and what you would save by bringing the rate down. (Disclosure: my company does this, as do others.)

If you hire a firm, check their experience. LinkedIn is a useful tool for looking at key people’s actual background. Does the team have real experience with the large processors? Do they require a contract? That is a risk, because if they do not deliver you may be locked out of using anyone else for the term. Do they use their own auditing software, or will they hand your private financial data to a third party to do the work? And get everything on company letterhead, signed by an officer. Emails and phone calls will not hold up if you end up in court.

Finally, make sure someone on your staff compares the fees every month and tracks whether anything went up or anything new appeared. If they spot a change, ask the processor to show you that exact change on the card network’s own published schedule. In other words, take control.

Going deeper on surcharging

If you have decided to look at surcharging seriously, three pages here go further than this one. The surcharge rules covers the network requirements in detail, surcharge laws by state covers the legal side, and surcharge versus convenience fee covers the distinction that catches most merchants out. If you would rather not surcharge at all, the cash discount program page covers the main alternative.

Check the fees before you pass them on
Send us a recent statement. If your effective rate comes back where it should be, surcharging is a problem you do not need to take on.

Get Your Free Audit

Get Your Free Audit  |  Schedule A Free Consultation

Subscribe to insights  |  Read more Insights  |  Submit an article idea


Read More

Check out our other insights here

Bank of America Credit Card Processing: What It Costs and What to Watch
Bank of America logo

If Bank of America handles your credit card processing, go and pull your last three statements before you read any further. We have watched accounts at that bank move from four basis points to over forty, and the businesses paying it were told the new
View

Do You Have Risk Fees On Your Credit Card Processing Statement?

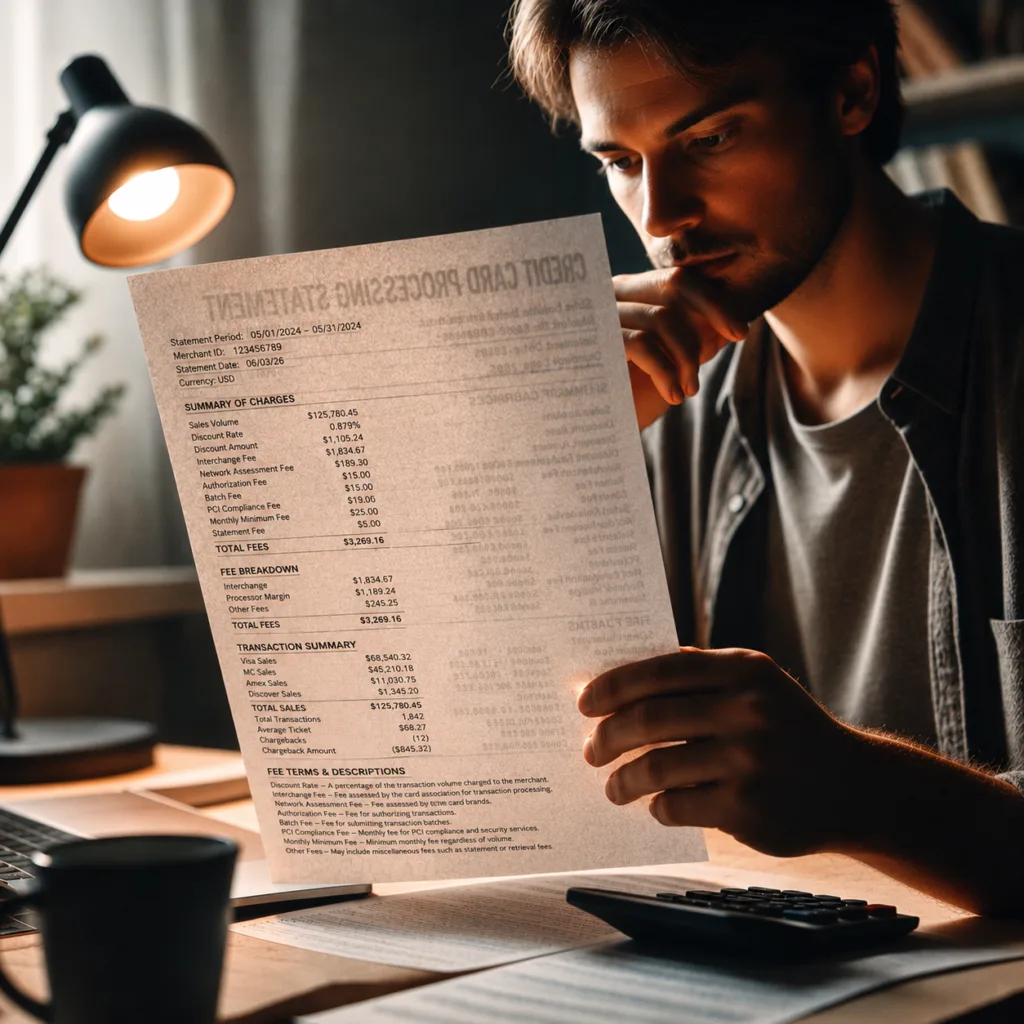
Man reading credit card processing statement

Do you have a “Risk Fee” on your credit card processing statement?

No? Good. You are luckier than a lot of merchants, and you should keep reading anyway.

View

Want to talk?

As seen on